Author: admin

  • Fire Protection Materials for EV Batteries to Exceed US$10B by 2037

    Fire Protection Materials for EV Batteries to Exceed US$10B by 2037

    Thermal runaway and system safety are critical topics when it comes to using lithium ion (Li-ion) batteries in electric vehicles. A key focus for the EV industry is the need to apply fire protection materials to prevent or delay thermal runaway propagating between cells and eventually outside of the battery pack. With growing regulatory momentum and safety standards, this article from IDTechEx looks at the outlook for fire protection materials market.


    Thermal runaway and system safety are critical topics when it comes to using lithium-ion (Li-ion) batteries in electric vehicles. While there are various methods for reducing the likelihood of thermal runaway, such as effective thermal management and active cooling solutions, quality control, and battery management systems, no method is 100% effective. Fire protection materials play a major role, serving as a passive method to prevent or mitigate the propagation of thermal runaway. Within the EV batteries market, IDTechEx forecasts that fire protection materials will grow at a CAGR of 13% over the next decade to exceed US$10 billion by 2037.

    Thermal Runaway and Fire Safety Standards

    There are several causes of thermal runaway, including overcharging, overheating, internal short circuits, and mechanical damage. For example, a manufacturing defect in any type of cell could cause an internal short circuit, that may lead to thermal runaway. Additionally, higher energy density cells generally exhibit higher temperatures during thermal runaway.

    With EVs becoming an increasingly large part of the fleet, their safety becomes ever more important. Although EV fires are statistically less common than fires involving internal combustion engines vehicles, safety cannot be overlooked at any rate of occurrence. As such, regulators are increasingly introducing stricter fire safety requirements for electric vehicles.

    For example, China was an early adopter of thermal runaway specific regulations, with a need to prevent fire or smoke exiting the battery pack for 5 minutes after the event occurs, among other requirements. China’s GB 38031-2025 mandated from July 2026 pushed forward with even stricter requirements for no fire or explosion under test conditions (i.e. 2 hours). Elsewhere, Europe and US mainly look to UC ECE regulations, though US’s FMVSS 305a has taken a less stringent standard for safety.

    Nonetheless, China’s GB 38031-2025 signals that the 5-minute escape time is unlikely to be sufficient for future regulations and more effective thermal runaway propagation measures will be necessary. Speaking to players, IDTechEx understands that several OEMs have started to target longer escape times in order to pre-empt future regulations and improve overall safety.

    Snapshot of Fire Protection Materials Market for EV Batteries

    A key focus for the EV industry is the need to apply fire protection materials to prevent or delay thermal runaway propagating between cells and eventually outside of the battery pack. These materials can be applied at the cell-level and at the pack-level. Materials applied at the cell-level are applied between or around the cells to help prevent propagation of thermal runaway from a specific cell. These typically include encapsulating foams, aerogels, compression pads (with additives), mica, and a few others.

    On the other hand, pack-level protection concerns materials that are used within the pack or as a coating of the pack but not directly between cells. These are generally designed to stop fire propagating between modules or outside of the pack. Typical materials in this application would be ceramic blankets (plus other non-wovens), aerogels, mica, powder coatings, intumescent coatings, and others.

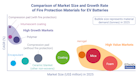
    Comparison of market size of fire protection materials in 2025 and projected growth over the next decade. Source: IDTechEx

    IDTechEx’s report on “Fire Protection Materials for EV 2027-2037: Markets, Trends, and Forecasts” looks at the different fire protection materials used at the cell-level and pack-level across vehicle types (cars, trucks, 2 and 3 wheelers, microcars, etc.). According to IDTechEx research, at present, materials with large market sizes include the likes of aerogels, mica, foam, together amassing a market revenue of over US$1.6 billion in 2025. On the other hand, although intumescent coatings, compression pads (with fire protection) and polymers captured a smaller share of the market size in 2025, IDTechEx forecasts strong growth for these materials over the next decade. 10-year market forecasts for market size and demand for materials at the cell- and pack-levels are available within the report.

    Outlook

    With evolving regulations, IDTechEx’s market forecasts show a greater adoption of fire protection materials. However, this must be paired with trends around battery development that can often reduce material use per vehicle. The variety of battery designs and material solutions presents a large opportunity across several markets and suppliers.

    IDTechEx’s report on Fire Protection Materials for Electric Vehicle Batteries analyzes trends in battery design, safety regulations, and how these will impact fire protection materials, with detailed benchmarks of fire protection materials. Using IDTechEx’s material database of over 150 materials from 72 suppliers, the materials covered include ceramic blankets/sheets (and other non-wovens), mica, aerogels, coatings (intumescent and other), encapsulants, encapsulating foams, compression pads, phase change materials, polymers, and several other materials. Each of these have more or less suitable applications, and the major categories are benchmarked in the report in terms of thermal conductivity, density, cost, and cost in the required application volume. 10-year market forecasts are included by material and vehicle category.

    For more information on this report, including downloadable sample pages, please visit www.IDTechEx.com/FPM, or for the full portfolio of research related to thermal management, advanced materials, batteries and EVs available from IDTechEx, see www.IDTechEx.com.
  • Cooling Down from High Power Demand with Thermal Management

    Cooling Down from High Power Demand with Thermal Management

    Thermal management strategies are the underdogs of modern technologies, reducing the risks of overheating in cases where exponentially increasing demand for power can lead to component temperatures rising. IDTechEx’s portfolio of Thermal Management Research Reports and Subscriptions explores thermal management developments across major sectors including data centers and electric vehicles.

    Keeping data centers cool

    Data centers are now significant contributors to power demand globally, with demand expected to keep rising in line with increasing high-performance computing, large language models, and AI use. In 2025, the total power for data centers stood at around 80GW, with this figure expected to surpass 250GW by 2035. The growth of hyperscalers such as Microsoft and AWS are expected to drive this rapid increase of power demand, alongside the increasing thermal design powers of GPUs and CPUs and overall computing capacities.

    IDTechEx’s report, “Thermal Management for Data Centers 2026-2036: Technologies, Markets, and Opportunities“, identifies multiple cooling approaches for data centers, categorized by air cooling, liquid cooling, and immersion cooling. Active air cooling can be done with a rear door heat exchanger, which takes heat carried away from the heat source using the convection of cold air, while liquid cooling takes a more immediate and direct approach. Direct-to-chip cooling or cold plate cooling is one liquid cooling method and can either be done in single-phase or two-phase. Immersion cooling, which sees an entire server placed within a tank of liquid for immediate effect, can also be done in single-phase or two-phase.

    Fire protection for electric vehicle batteries

    Electric vehicle batteries, despite being one of the main contributors to reduced reliance on fossil fuels within the transportation sector, have been known to cause fires as a result of thermal runaway. The electric vehicle industry as a whole sees multiple battery chemistries used, depending on vehicle type and requirements for size, energy density, and charge times, though Li-ion batteries are widely discussed within IDTechEx’s report, “Fire Protection Materials for EV Batteries 2027-2037: Markets, Trends, and Forecasts“, as being the dominant type.

    Opting for solid-state electrolyte in the place of more flammable liquid electrolyte is one approach to reducing fire hazards and improving a battery’s thermal stability. Solid-state batteries have a wider operation temperature range and can lead to less heat generation in the event of external heating failure, according to IDTechEx. Alongside this, their heat dissipation is notably better than with liquid electrolyte batteries, meaning hot spots are less likely to form. There are still dangers of using solid-state electrolyte batteries, such as harmful gases that can be created though reactions with moisture, though they still provide improved overall safety. However, solid state batteries are a less mature technology and do not have the same market capacity as Li-ion batteries.

    Na-ion batteries are also explored within IDTechEx’s report as being a safer alternative to Li-ion. They are able to be stored at 0V without performance impact, and at 0% state of charge, heat generation is lower. Additionally, Na-ion batteries would see thermal runaway at higher temperatures than in Li-ion batteries, as well as a slower impact.

    Fire protection in the form of regulations is also covered by IDTechEx, as the report provides research on different regions worldwide. In Europe, a 5-minute warning is required to make passengers aware of a thermal event that has started before it is visible outside the batter pack, while in China, the requirement is that the battery should not catch fire or explode for 2 hours after thermal runaway, highlighting a more advanced approach to safety.

  • The Shapeshifting Automotive Market – EVs and Autonomy

    The Shapeshifting Automotive Market – EVs and Autonomy

    The landscape of transportation looks vastly different today than it did two decades ago. The introduction of electric vehicles and autonomous vehicles is not only having positive environmental impacts as combustion engines gradually fade out, but passenger safety has never been such a high priority. IDTechEx’s portfolios of Electric Vehicles Research Reports and Subscriptions and Robotics & Autonomy Research Reports and Subscriptions cover the realms of recent vehicle advancements.

    The diversity of the EV landscape

    Electric vehicles encompass multiple types of cars powered by electricity instead of traditional combustion engines which contribute towards harmful emissions. The fleet may include the classic battery-electric vehicle (BEV), plug-in hybrid electric vehicle (PHEV), fuel cell electric vehicle (FCEV) and more. These can also be categorized into plug-in and non-plug-in, with FCEVs, for example, running on hydrogen in a fuel cell which creates electricity.

    In the passenger car market, IDTechEx’s report, “Electric Vehicles: Land, Sea, and Air 2025-2045“, predicts 70 million sales in 2045, compared with 14.4 million in 2023, highlighting strong growth to come within the biggest segment of electric vehicles. Light commercial vehicles are expected to see 11 million sales in 2045, and trucks 1.7 million, also contributing to the demand for electric vehicles across multiple sectors, including logistics and deliveries, where many companies may choose to opt for electric vehicles as a way to minimize carbon emissions and footprints. Construction vehicles becoming electrified is another trend expected to see increased uptake, for quieter and emission-free building sites.

    However, it isn’t just large vehicles becoming electric. Micro EVs are expected to see 66 million sales in 2045, following closely behind passenger cars, and will see the most uptake in regions such as Asia where they are common forms of transportation for getting around busy cities and built-up areas. The electrification of two and three-wheeler vehicles is also a more feasible and cheaper option, with smaller battery demands and less materials required overall. Micro vehicles also have many other benefits alongside affordability, including compact designs, light weight, low energy consumption, simple operation, and ease of parking. IDTechEx’s report, “Micro EVs 2026-2046: Electric Two-Wheelers, Three-Wheelers, and Microcars“, covers the developments and forecasts within this particular market, highlighting current trends across battery chemistries that are particularly sought-after for these applications.

    Multifaceted autonomy

    In parallel to electric vehicle technology advancing, autonomous vehicles are another trend that is sweeping the automotive industry. From in-cabin systems to external radar, cars manufactured today have many safety features included that make part of the advanced driver assistance system (ADAS). In-cabin sensing is one phenomenon which encompasses a multitude of technologies such as capacitive sensors for hands-on detection, ECG sensors in the steering wheel to monitor the driver’s heart rate, infrared cameras for gaze and head motion tracking, and radars for features such as gesture control and occupancy detection. IDTechEx’s report, “In-Cabin Sensing 2025-2035: Technologies, Opportunities, and Markets“, explores how in-cabin sensing systems can be split into the driver monitoring system (DMS) and the occupant monitoring system (OMS), with many technologies crossing over the two, achieving maximum safety coverage.

    Distraction and drowsiness monitoring with infrared cameras can also work alongside artificial intelligence to decipher the driver’s state of attention. This can allow the car to suggest ordering a coffee from the next service station and place an order using biometric authentication. IDTechEx’s report, “Autonomous Driving Software and AI in Automotive 2026-2046: Technologies, Markets, Players“, covers the avenues through which driving experiences can become as personalized as possible, with favourite radio stations and seating preferences of individuals also being remembered upon entry to the vehicle.

    Radar technology in vehicles, some of the latest developments for which are covered in IDTechEx’s report, “Automotive Radar Market 2025-2045: Robotaxis & Autonomous Cars“, can allow for safer driving by enabling automatic features such as automatic emergency braking (AEB) and adaptive cruise control (ACC), which 71% of new cars were fitted with in 2023. IDTechEx’s research covers short-range and long-range radar systems, and the features specific to both.

    Information gathered from radar can be fed back to intelligent software systems and allow vehicles to communicate with other vehicles on the road. They can then work together to make up a real time map and build an idea of where traffic jams or incidents may be occurring. IDTechEx’s report, “Software-Defined Vehicles, Connected Cars, and AI in Cars 2026-2036: Markets, Trends, and Forecasts“, covers communications between cars and the ways autonomous software is developing to make driving safer and more streamlined.

  • Battery Storage for Data Centers and Safer with Solid State Batteries

    Battery Storage for Data Centers and Safer with Solid State Batteries

    The battery sector is rapidly growing in multiple directions, with battery storage technologies expected to be responsible for powering many major sectors including data centers and 6G power stations, and solid-state batteries gaining increasing amounts of attention for their safer chemistries. IDTechEx’s portfolio of Batteries & Energy Storage Research Reports and Subscriptions covers the latest trends and developments within the large battery market.

    The growing demand for data center power

    The battery storage market has seen increased growth in line with energy and power demand ramping up, with data centers in particular expected to become an increasing driver of power demand. Across the US, Europe, and China, data centers are likely to see developments and advancements surrounding the ways in which they are powered, with long duration battery technologies expected to be used in the future as this approach becomes more mainstream and necessary for supporting power demand. Switching to long duration technologies will also help with improving grid flexibility.

    IDTechEx’s report, “Battery Storage for Data Centers, Commercial & Industrial Applications 2026-2036: Market, Forecasts…“, identifies that although data centers, in particular hyperscalers, will be a primary driver for battery storage demand over the next few years, 5G and 6G base stations are likely to take over in the 2030s as a result of growth in China and other regions. Battery energy storage paired with EV chargers will also maintain its prevalence as more vehicles become electrified and more charging infrastructure is needed globally. Over the next decade, the demand for global commercial and industrial (C&I) lithium-ion battery energy storage systems (BESS) is expected to jump from 22GWh to 108GWh in 2036, while the commercial and industrial sector in particular will see a compound annual growth rate of 17.4% during the same period eventually reaching a value of US$21.3 billion. It is not just large players operating at grid scale that are expected to be contributing to this growth, but smaller C&I BESS manufacturers that may be able to target market shares not yet dominated by bigger companies.

    New battery chemistries are also expected to be adopted within the battery storage sector, such as redox flow batteries and Na-ion for data centers, as a result of not only demand for longer cycle life and lower degradation, but safer technologies that don’t use flammable electrolyte. Na-ion batteries in particular are named by IDTechEx as a technology which could be used for discharging at high rates, meaning applications like volatile AI compute loads could be more easily managed.

    Solid-state safety and improved performance

    Solid-state chemistries are renowned for improved safety in their move away from flammable liquid components, which as outlined in IDTechEx’s report, “Solid-State Batteries 2026-2036: Technology, Forecasts, Players“, can be hazardous in a number of ways. Conventional lithium-ion batteries commonly use flammable liquid electrolytes based on organic carbonate solvents. Several widely used linear carbonates have relatively low flash points and high volatility, increasing fire risk if the cell is damaged, overheated, or leaks. In addition, the commonly used conducting salt LiPF₆ can decompose or hydrolyze in the presence of moisture and under thermal-abuse conditions, generating corrosive and toxic HF-containing species that may degrade cell components.

    Solid-state batteries can also provide more flexibility in shape and form factor design, which isn’t possible when the right stacking of materials in a conventional Li-ion battery needs to be considered. Solid-state batteries can also either be thin film or bulk, meaning there are more options available, and more applications that can be targeted. In terms of performance, IDTechEx states that conventional electrolyte is usually compatible with low-voltage cathodes, whereas with a solid-state electrolyte, high voltage cathodes and high-capacity anodes can be used, meaning the output practical energy density can be increased.

  • The Expansion of Electric Vehicle Tech with IDTechEx

    The Expansion of Electric Vehicle Tech with IDTechEx

    Electric vehicles are continuing to play a vital role in decarbonizing the transport industry as they help with the shift away from fossil fuel reliance with their utilization of battery technologies. IDTechEx’s portfolio of Electric Vehicles Research Reports and Subscriptions is home to a well-rounded overview of the electric vehicle sector, and includes different vehicle types, materials, and thermal management strategies.

    Micro EVs for cityscapes

    Micro vehicles including two-wheelers, three-wheelers, and microcars have long been a huge target for electrification, due to their smaller size and presence within cities as well as their use for delivery applications. The many short journeys these vehicles make across built-up areas mean that recharging should not be an issue, as charging stations are likely to be more widely available in cities than in rural areas, while also creating frequent opportunities for regenerative braking. IDTechEx’s report, “Micro EVs 2026-2046: Electric Two-Wheelers, Three-Wheelers, and Microcars“, explores drivers for micro EVs, including their nimble nature and ability to weave through traffic, alongside the lower cost of electrification when compared with larger vehicles like passenger cars and trucks. The smaller battery size and weight mean they can be cheaper to manufacture and maintain, and easier to deploy. Micro EVs, particularly two-wheelers, have a dominant presence across Asia, where they have long been used within big cities. IDTechEx also reports that grants for micro-EV purchasing are in place as an incentive for the movement away from combustion vehicles.

    Materials and thermal management strategies

    While lead-acid batteries are commonly used for micro EVs, lithium-ion batteries are widespread for larger electric vehicles. Li-ion batteries could prove to be a better alternative for micro EVs, with improved performance and less need to be replaced, while also recently being subject to reductions in price. With multiple Li-ion chemistry options for EVs ranging from NMC, LFP, and LMFP, depending on vehicle type or performance requirements, the landscape for EV battery development is sizable. The increase in global environmental regulations affecting the EV market, including emission regulations, is also pushing uptake, and raising battery material demand globally. IDTechEx’s report, “Materials for Electric Vehicle Battery Cells and Packs 2026-2036: Technologies, Markets, Forecasts“, predicts that the global material demand for EV battery materials will reach 22.2 million tonnes by 2036, growing at a compound annual growth rate of 11.8%, highlighting the expected success of the EV market.

    Many of the materials accounted for within this 2036 figure are those for thermal management systems within electric vehicles, which are necessary to ensure risks of thermal runaway and fires are minimized. Batteries, motors, and other EV components each have their own optimal operation temperatures, with IDTechEx’s report, “Thermal Management for Electric Vehicles 2026-2036: Materials, Markets, and Technologies“, exploring each component individually and the ranges either side of their optimal temperatures at which performances may begin to decline or lose efficiency.

    Thermal interface materials, fire protection materials, thermal management strategy, and heat pumps and architecture are four battery thermal management categories outlined within the report, each with their own intra-competitiveness between materials. Ceramics, mica, aerogels, foams, encapsulants, and coatings, are just some of the material options for fire protection, each with their own benefits and drawbacks. For thermal management, air (passive or forced), liquid (water-glycol), refrigerant, phase change materials, and immersion are all potential strategies, showing the vast landscape for EV thermal management that exists as a result of the importance of safety prioritization. IDTechEx’s report dives into forecasts for the uptake of different material types spanning the next decade.